
By James Neals, CFA®
Vice President & Portfolio Manager, Optimize Financial Group
“George Chuvalo is the toughest guy I ever fought.” — Muhammad Ali
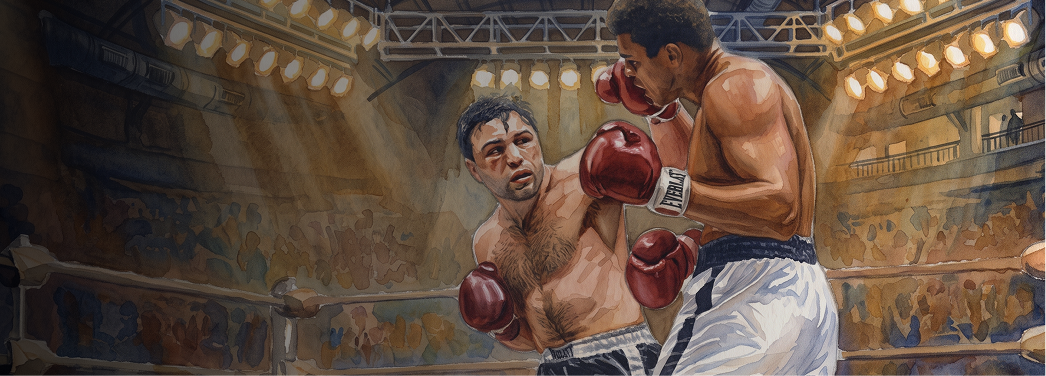
Canada recently lost an icon with the passing of George Chuvalo, one of the toughest fighters this country has ever produced. His fight with Muhammad Ali in 1966 at Maple Leaf Gardens in Toronto is the stuff of Canadian sporting legend. Chuvalo was given only 17 days' notice to prepare, stepped into the ring against arguably the greatest boxer of all time, in Ali’s prime, and shocked the world by going the full 15 rounds. Ali won the fight by unanimous decision, but the story afterwards says almost as much about Chuvalo as the fight itself: Ali was pushed to the full 15 rounds for the first time in his career and had to be taken to St. Michael's Hospital in Toronto for internal bleeding post-fight. Meanwhile, Chuvalo took his wife out dancing downtown after the fight. Although no one will ever challenge Chuvalo’s toughness, markets today certainly are showing their own form of grit. The market has taken some serious punches this year: higher oil prices, geopolitical uncertainty, elevated Treasury yields, currency volatility, and persistent concerns around inflation. Yet, like Chuvalo, every time you think the market should finally go down for the count, it gets back up and keeps coming forward.
Higher oil prices should pressure consumers and inflation expectations. Higher bond yields should put pressure on equity valuations. Geopolitical uncertainty should increase risk premia. But the market keeps taking the punch. That doesn’t mean the risks have disappeared, or that equities are immune to a larger shock. It simply means the market’s capacity to absorb bad news has been considerably stronger than many investors expected. George Chuvalo was never once knocked down in his professional career (in 93 pro fights), and the equity market is starting to look like it has inherited some of that toughness. Speaking of taking punches, the bond market has taken even more in 2026…that said, the bond market has already absorbed a significant amount of the tightening. Interest rates have risen meaningfully, borrowing costs are higher, and investors are already anticipating a more restrictive policy environment. The opportunity from here is that higher yields via rhetoric may ultimately do the job for central banks without them having to start a new hiking cycle.
In summary, equities have spent 2026 taking punches from oil shocks, higher yields, geopolitical risk, and macro uncertainty, yet somehow keep getting back up. The bond market, meanwhile, may be getting closer to throwing a few punches of its own. With the Fed having just delivered its first hike since 2023 and the data calendar relatively light, I expect geopolitics to do most of the heavy lifting this week. The key risks are Thursday’s Trump-Xi meeting, the oil and geopolitical risk around Iran and the Strait of Hormuz, and how Fed officials frame the path forward after last week’s hike. So while the economic calendar may be relatively quiet, there is still plenty for markets to digest, and potentially, for investors, plenty of opportunity in the volatility.
3 Things We’re Watching This Week
- The federal government is significantly expanding its “productivity mega deduction,” allowing businesses to immediately expense capital spending across a much wider range of assets. This now includes energy infrastructure, mining property, aircraft, fibre-optic cables, Canadian-made vehicles, computer equipment, bridges, and roads. The measure applies to property purchased from September 15 onward and is intended to be permanent.
- The expansion is significant: roughly two-thirds of the asset categories businesses invest in will now qualify, up from about 15%. The government estimates the measure could support roughly C$22 billion of additional annual economic output and 80,000 additional jobs per year a decade from now.
- The goal is to address Canada’s longstanding challenge of weak business investment and productivity. The government estimates the changes will lower the effective tax rate on new business investment to 6.4% from 13%, potentially making Canada more competitive for new investment.
- What we’re watching: Whether these incentives lead businesses to meaningfully increase capital spending, particularly across energy infrastructure, mining, manufacturing, and technology.
- Why it matters: Stronger business investment can support productivity, job creation, and economic growth. If companies respond by putting more capital to work in Canada, it could help strengthen the country’s longer-term growth outlook.
2. How Do Stocks Digest a Fed Hiking Cycle?
- Stocks have historically experienced some weakness at the beginning of Federal Reserve hiking cycles, with smaller companies often seeing the greatest initial pressure. Once rate hikes begin, markets generally need time to adjust to the higher-rate environment.
- Historically, average equity returns have been negative one month after the start of a hiking cycle. By six months, however, average returns had generally turned positive, with a similar pattern evident over 12 months.
- What we’re watching: Whether higher rates create the typical period of near-term volatility and how quickly markets adjust, particularly among smaller companies and the broader equity market.
- Why it matters: History suggests the beginning of a hiking cycle can create short-term volatility without necessarily leading to a prolonged market downturn. For long-term investors, the important question is how corporate earnings and the economy hold up as markets adjust to higher rates.
3. Canada’s EU Pivot: How Much Deeper Can the Relationship Go? -
European Commission President Ursula von der Leyen has proposed a new “associate member” relationship between Canada and the EU. While details remain limited, the arrangement could potentially give Canada greater access to European markets and deepen cooperation in key industries.
-
The opportunity could extend beyond traditional trade. Canada and the EU have identified manufacturing, technology, defence, energy, and the Arctic as areas for greater cooperation, while Canada is already participating in the EU’s €150 billion SAFE defence-procurement program.
-
Canada already has significant European market access through CETA, but its economic relationship with the U.S. remains much larger. Canada-EU goods trade was approximately C$134 billion last year, compared with more than C$800 billion of trade with the U.S., highlighting both the opportunity for diversification and the importance of maintaining existing North American relationships.
-
What we’re watching: What an associate relationship would actually include, particularly around market access, energy, defence, technology and investment.
-
Why it matters: A deeper relationship with Europe could give Canadian businesses greater access to new markets and investment opportunities. The longer-term impact will ultimately depend on the specific agreements Canada and the EU are able to negotiate.
Disclaimer: This report is for informational purposes only and does not constitute investment advice. Please consult with your financial advisor before making any investment decisions.